THE REPRICING WINDOW: MENDRIA'S MOTIVATION
Every real asset has two prices. There is the price in the model: the appraisal, the DCF, the cap rate, the value carried into the next committee meeting. And there is the price forming outside the model: in lender questions, insurance renewals, buyer diligence, infrastructure constraints, capex needs, and regulatory pressure.
For a while, the two prices can look identical: NOI holds. The appraisal stays flat. The asset still screens as stable. But the built world has always had a strange problem: the most important changes are often invisible until they are expensive.
An office tower can still show stable NOI while lenders quietly reduce proceeds. A data center can have record tenant demand while a delayed power upgrade changes the value of its next phase. A port can keep moving cargo while insurers begin pricing downtime risk differently. A museum can look stable in a facilities plan while HVAC, humidity, flood, and insurance exposure turn deferred maintenance into a collections, donor, and capital-campaign problem.
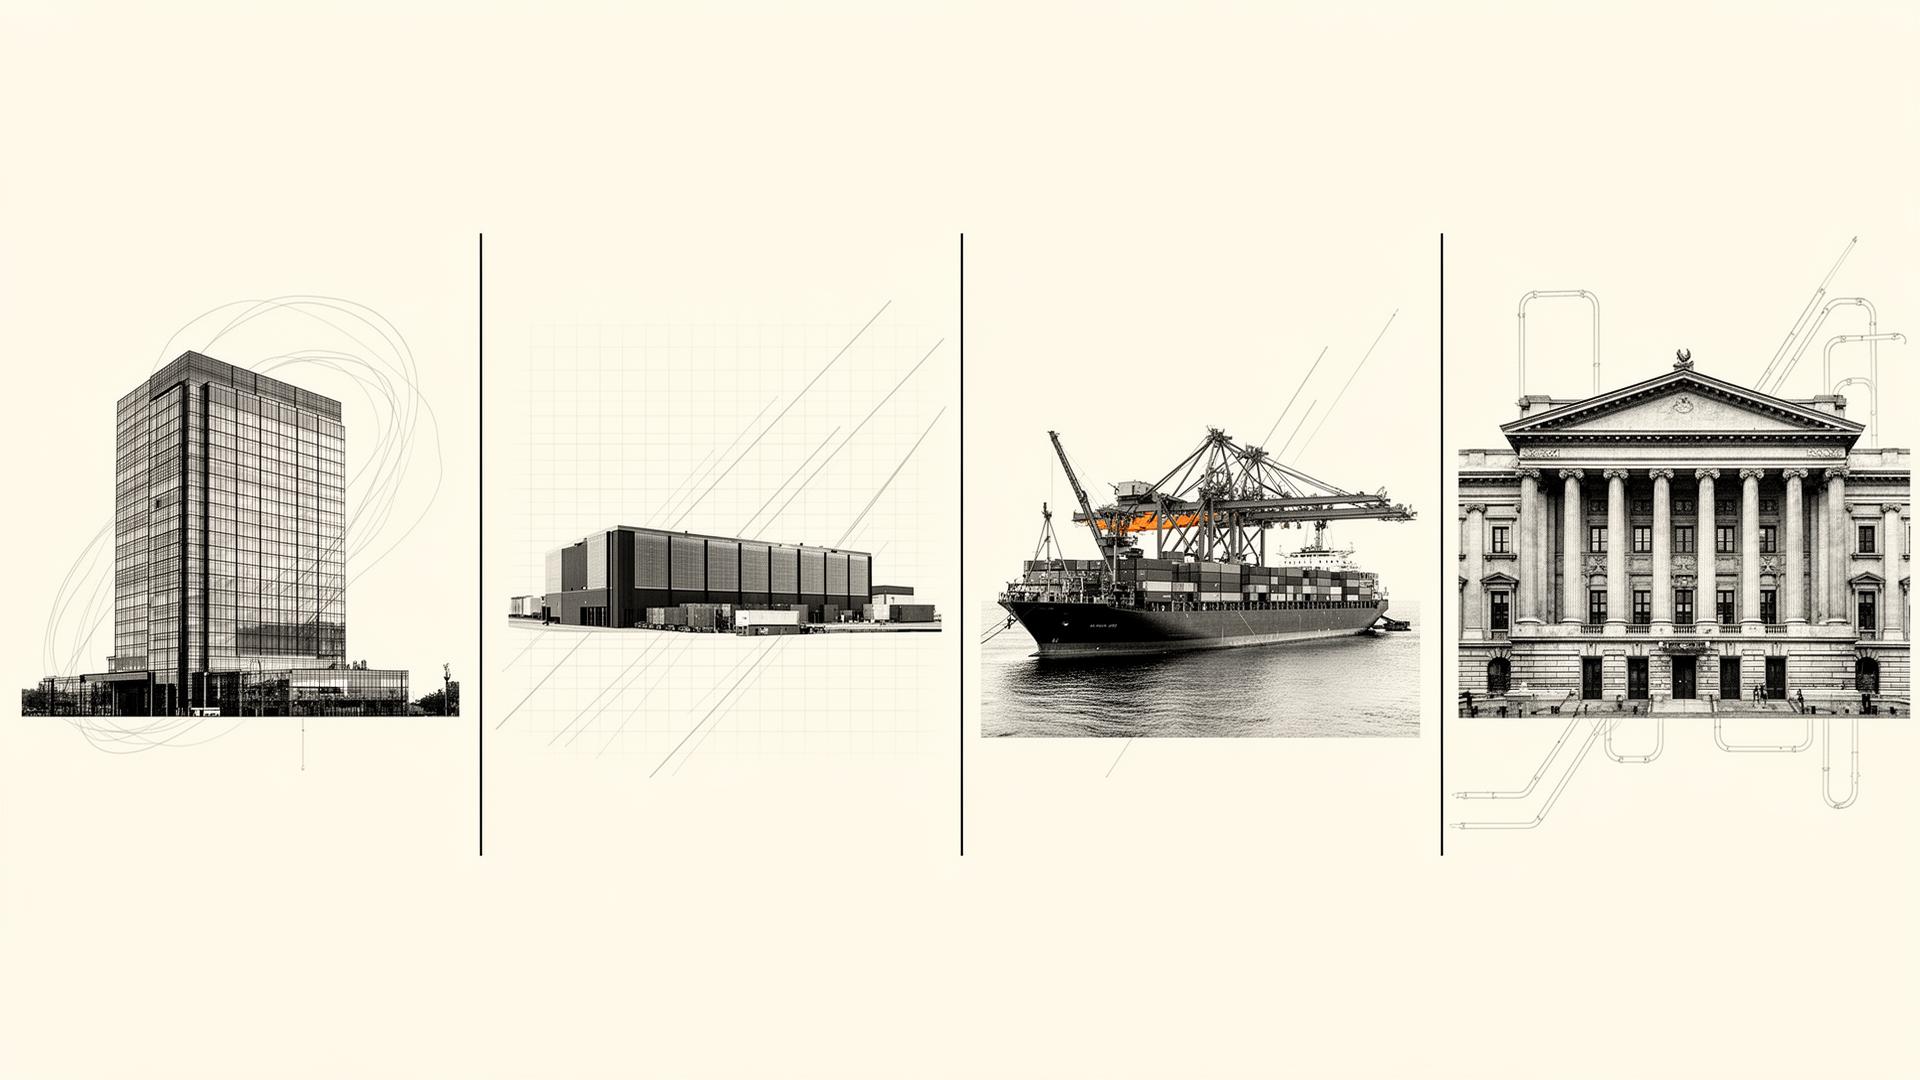
Nothing has obviously broken: the model still works, the appraisal has not moved, the headline performance still looks fine. But the market is already changing the price.
We believe the most important real asset decisions happen in the gap between those two prices. We call this the repricing window: the months or years between the first signal and the forced adjustment, when owners still have time to act, defend value, improve terms, and turn early insight into an underwriting edge. And we created Mendria to make that invisible interval measurable.
A trillion-dollar refinancing cycle is colliding with a built world that still gets underwritten too late. In 2025, roughly $957 billion of U.S. commercial and multifamily mortgage debt was scheduled to mature. In 2026, another roughly $875 billion is maturing. At the same time, commercial property pricing has begun to stabilize in aggregate, but remains uneven by asset class, market, and capital need. Green Street reported that its U.S. all-property index rose 2.4% over the twelve months ending January 2026, a sign of stabilization rather than a full reset.
That's why this moment matters. The obvious distress cycle may be easing, but the underwriting problem is becoming more structural. The next cycle will not punish every asset equally. It will reward owners who can see which properties are becoming more financeable, more insurable, more resilient, and more defensible, and penalize those who wait for the model, appraisal, or lender term sheet to confirm what the market already knew.
For decades, real asset underwriting could rely on relatively stable assumptions: historical cash flow, appraisals, comps, cap rates, and periodic diligence. That world is changing. Insurance repricing, lender proceeds cuts, energy volatility, regulation, deferred capex, infrastructure constraints, climate exposure, and buyer retrades often appear before NOI, appraisals, or headline performance show a problem.
The cost of missing that window is large. On institutional assets, that 3–8% is consistently $5M to $25M+ of value per property: on a $250M asset, $7.5M to $20M. Across a $1B portfolio, it compounds to $30M to $80M+ of hidden value at risk, and because exit value is a multiple of EBITDA, what looks like an operating-line cost lands as multiple compression at sale. But that same window can also become an underwriting edge. If owners see the pressure early, they can sequence capex, prepare lender evidence, improve insurance posture, adjust reserves, defend pricing, or sell before the discount becomes unavoidable.
We started Mendria because risk identification is no longer enough. Owners need to know which headwinds are becoming material, which assets they hit first, how much value is at stake, and what actions create or protect the most value. A risk you can't size is a risk you freeze on; a risk you can size is a decision you can make: fund the fix or don't. We make resilience financially measurable by connecting the signals usually evaluated in silos (debt, insurance, regulation, engineering, operations, capex, asset condition, infrastructure, climate, and buyer behavior) into one forward-pricing view. We're a decision platform for acquisitions, ownership plans, refinances, insurance renewals, capital allocation, board discussions, and exits.
Our belief is simple: the next generation of real asset winners will not just own better buildings. They will see repricing earlier, act faster, and turn fragmented market signals into value-creation decisions before everyone else sees the discount.